What Does A Mortgage Broker Actually Do?
From first conversation to completion, discover what your mortgage advisor is doing behind the scenes.
Quick Answer
A mortgage broker does much more than find a competitive mortgage rate. At The Mortgage Advice Group, the process starts by understanding what you want to achieve and your individual circumstances.
Behind the scenes, your adviser researches lenders, products and lending criteria to identify options that are viable before submitting your application and supporting documents.
Once submitted, a dedicated case manager helps progress the application through to legal completion, providing support and liaising with lenders, solicitors and estate agents where needed.
If problems arise, such as a property being down-valued, your adviser can also help explore possible solutions and work with the parties involved to keep the application moving.
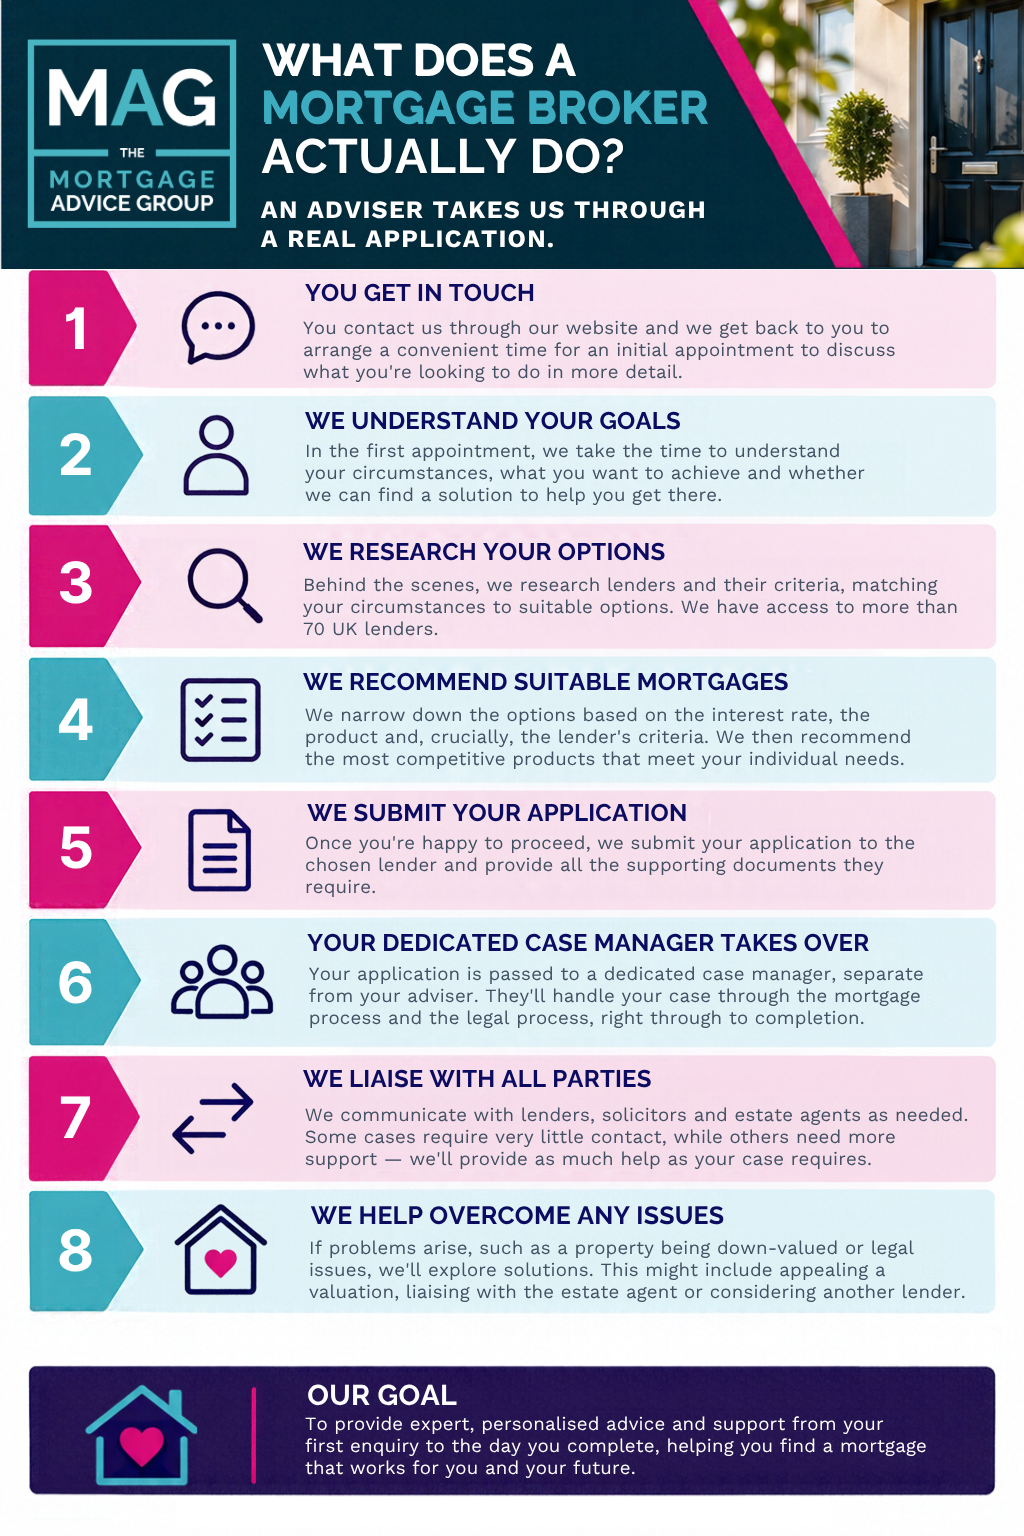
An adviser takes us through a real application
For many people, the visible part of using a mortgage broker is relatively straightforward: you have an appointment, provide some information and eventually receive a mortgage recommendation.
But there can be a considerable amount happening behind the scenes between that first conversation and the day the transaction legally completes.
At The Mortgage Advice Group, the process involves understanding what the client wants to achieve, researching lenders and their criteria, recommending a suitable mortgage, submitting the application and then helping to progress both the mortgage and legal sides of the transaction.
The team has connections with more than 70 UK lenders, while its dedicated after-sales team helps progress applications and provides clients with a dedicated case handler once an application has been submitted.
So, what does that process actually look like in practice?
What happens from the moment somebody first contacts you?
A mortgage application often starts with something as simple as an enquiry through the website.
Once somebody gets in touch, the first step is normally to communicate with them and arrange a fixed appointment where an adviser can discuss what they’re looking to do in more detail.
The Mortgage Advice Group offers face-to-face appointments from our Redditch and Birmingham offices, as well as telephone and video appointments for clients who can’t or don’t want to visit an office.
That initial conversation isn’t about immediately choosing a mortgage. It’s about first understanding the person behind the application.
What are you trying to establish during the first appointment?
The key question is: what does the customer actually want to achieve?
During that first appointment, the mortgage adviser wants to understand the client’s circumstances, their goals and what they’re ultimately trying to accomplish. From there, they can begin establishing whether there’s a mortgage solution that could help them achieve it.
“We’re trying to establish what the customer’s looking to achieve, what their goals are and, ultimately, whether we can find a solution that helps them achieve that.”
The information required will depend on the individual case. The Mortgage Advice Group will typically ask for identification, proof of income and bank statements initially, with a more specific list provided according to the client’s circumstances.
The individual approach is important because two people looking to borrow a similar amount may still have very different circumstances.
What work happens behind the scenes that clients don't see?
A significant part of a mortgage broker’s job happens away from the client appointment: research. The adviser researches lenders and looks at how the client’s individual circumstances fit with the options available.
The Mortgage Advice Group has connections with more than 70 UK lenders, so the job isn’t simply to look down a list and find the lowest advertised interest rate.
We need to establish which lenders and mortgages could actually work for that particular client. This is where understanding lender criteria becomes particularly important.
How do you narrow dozens of lenders down to suitable options?
The research undertaken behind the scenes allows the adviser to start narrowing the available choices.
There are several elements to consider together. The adviser looks at the rate, the product and, crucially, the lender’s criteria.
A mortgage might appear competitive on rate, but that’s of little use if the client’s circumstances don’t meet the lender’s requirements.
The aim is therefore to identify the most competitive products the adviser can while making sure the proposed application can still meet the relevant lender’s criteria. This reflects our wider approach of providing advice tailored to an individual’s circumstances rather than treating every mortgage application in the same way.
What happens once you've submitted an application?
Submitting the application isn’t the end of the broker’s involvement. Once an application has gone to the chosen lender, The Mortgage Advice Group provides the supporting documentation requested for the case.
The application is then passed to a dedicated case manager, separate from the mortgage broker.
This is an important part of how we handle applications. Its after-sales team proactively progresses cases, works with lenders to provide requested documents and information, supports clients with legal paperwork and follows communication with solicitors and other parties through to completion.
In other words, clients aren’t simply left to manage everything themselves once the mortgage application has been sent.
The case manager helps handle the application through the mortgage process and into the legal process until the transaction legally completes.
How much contact do you have with lenders, solicitors and estate agents?
There isn’t one answer because every transaction is different.
Some cases require relatively few touchpoints. A client may be very self-sufficient and the solicitor may progress matters efficiently without requiring much additional input.
Other transactions need significantly more support.
Our approach is to provide as much help and involvement as that individual case requires to get it where it needs to be.
That can mean communication with lenders, solicitors and estate agents as circumstances develop.
These relationships are also part of the team’s experience. Founder and director Kate McTernan has worked as a mortgage expert for more than 15 years and has developed strong relationships with clients, solicitors and estate agents during that time.
At what stages do mortgage applications most commonly run into problems?
Problems can emerge even after the client has received a mortgage offer.
One area where complications can arise is during the legal process. The solicitor also acts for the lender, and there can be something about the property that needs to be reported back to that lender. That means an issue can emerge during the legal work that wasn’t known when the original mortgage application was submitted.
Property-related issues are another common source of problems. For example, a lender might down-value a property or be unhappy with something concerning the property itself.
Difficulties can also arise when information comes to light after the application that the adviser wasn’t previously aware of because it hadn’t been disclosed by the client.
This is one reason the work after submission can be just as important as the initial research. A mortgage application isn’t necessarily a straight line from submission to completion, and somebody may need to deal with issues as they arise.
How adviser support can make a difference when problems arise
A property being down-valued by a lender is a good example of where having a mortgage adviser involved can make a real difference.
If you’ve agreed to purchase a property for a certain amount but the lender’s valuation comes back lower, it can put the transaction in a difficult position. However, that doesn’t necessarily mean the purchase has to come to an end.
We’ve dealt with cases where we’ve gone back to the lender and appealed the valuation, providing comparable properties to support the price our client has agreed to pay. Depending on the circumstances, we may also speak directly with the estate agent on our client’s behalf to see whether the purchase price can be renegotiated.
Another option can be to revisit our lender research. If there’s a suitable alternative, we may be able to place the application with another lender, whose valuation of the property may be different.
This is where our role goes beyond simply finding a mortgage product and submitting an application. When an unexpected issue arises, we’ll look at the options available and work with the relevant parties to try to find a way forward.
Our support doesn’t stop once your mortgage application has been submitted either. Your case is passed to a dedicated case manager, who helps progress your mortgage and supports you through the legal process until completion.
“If a property is down-valued, we can go back to the lender and appeal it with comparable properties, speak to the estate agent about renegotiating the price, or look at whether there’s another suitable lender. We’re always very involved when issues like that come up. Whatever the problem is, we will do everything that we possibly can within our expertise to make it better.”
Our Locations
Prospect House, Church Green West, Redditch, B97 4DJ
301 Pershore Road South, Kings Norton, Birmingham, B30 3EX
The Mortgage Advice Group is a trading name of McTernan Financial Limited an Appointed Representative of Primis Mortgage Network, a trading name of Advance Mortgage Funding Limited which is authorised and regulated by the Financial Conduct Authority. Registered Office: Prospect House, Church Green West, Redditch B97 4DJ. Registered in England and Wales. Company number: 09168296.
Birmingham Mortgage Advice is a trading name of McTernan Financial Limited an Appointed Representative of Primis Mortgage Network, a trading name of Advance Mortgage Funding Limited which is authorised and regulated by the Financial Conduct Authority.
Redditch Mortgage Advice is a trading name of McTernan Financial Limited an Appointed Representative of Primis Mortgage Network, a trading name of Advance Mortgage Funding Limited which is authorised and regulated by the Financial Conduct Authority.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE
The Financial Conduct Authority does not regulate all Buy to Let mortgages
We charge an arrangement fee of £495 which is payable when a full application is made to a lender. Your adviser will agree your arrangement fee with you before commencing any chargeable work.
The guidance and/or advice contained within this website is subject to the UK regulatory regime and is therefore primarily targeted at consumers based in the UK.
Trackbacks/Pingbacks